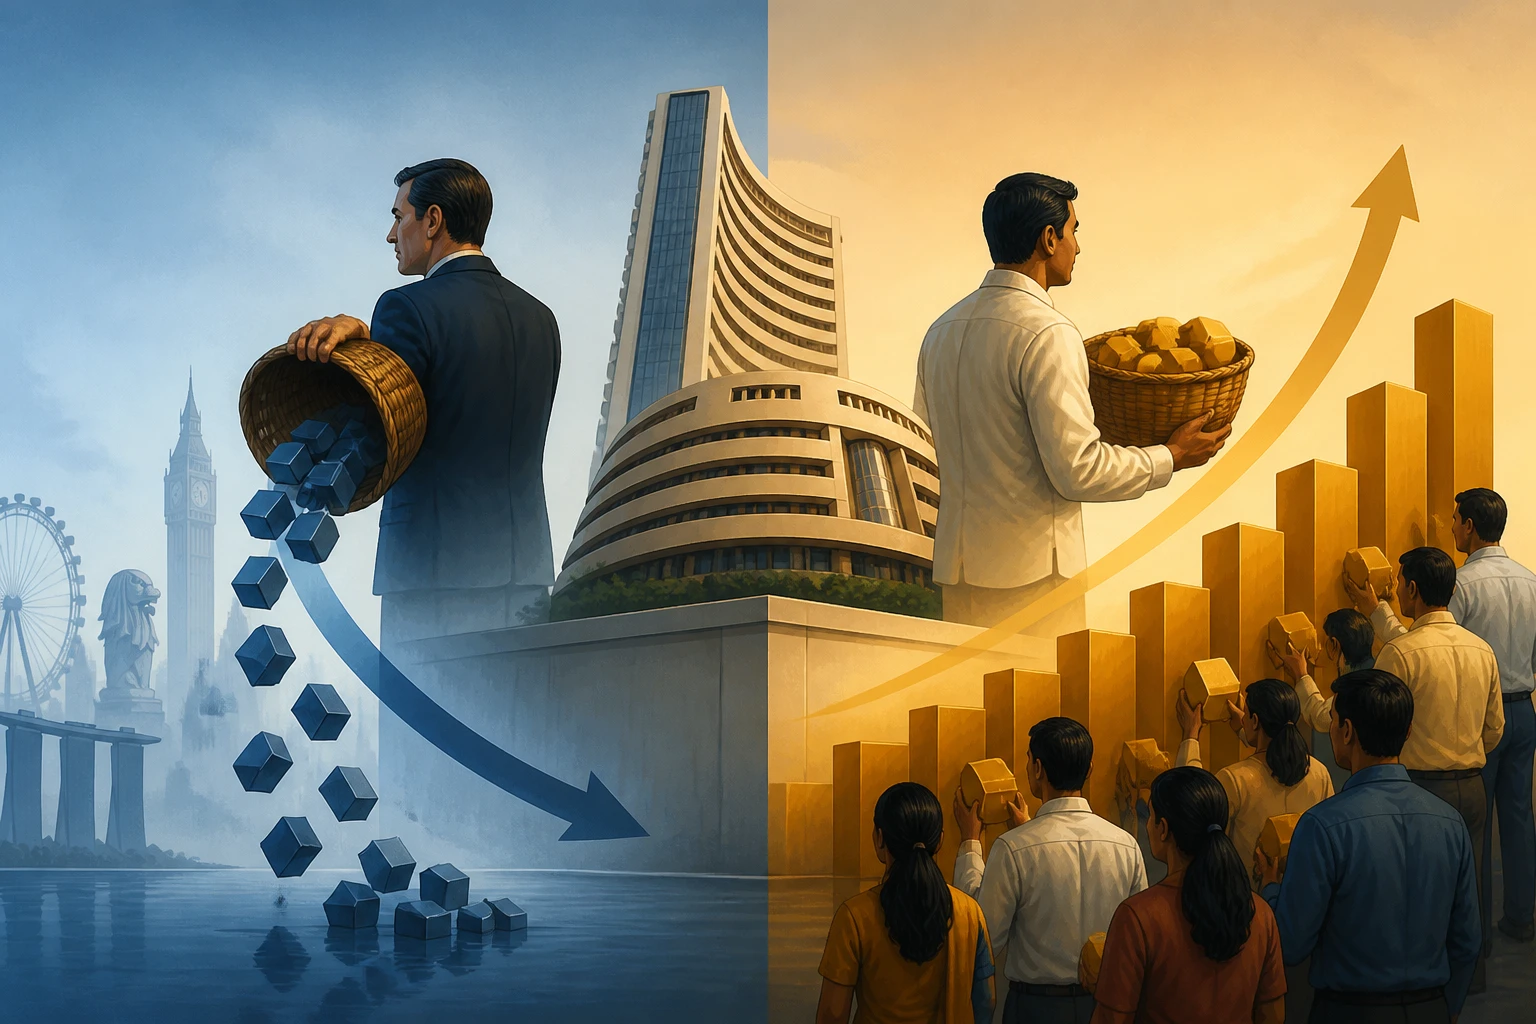
A multi-family office quietly exited its entire Indian equity portfolio this year. At roughly the same moment, Indian retail investors poured ₹29,328 crore into equity mutual funds in August alone — up 19% from July, and the 66th consecutive positive month for equity fund inflows.
Same market. Opposite directions. Both sides convinced they're right.
Why Foreigners Are Leaving
India has replaced Indonesia as Asia's least-preferred stock market in the Bank of America fund manager survey, signalling growing caution toward a market that's among the world's worst performers this year. The reasons are layered. The lack of clear AI exposure remains the key concern, with weak growth and high valuations also cited for the bearish outlook.
The structural numbers are stark. FPI ownership in NSE-listed companies dropped to a 17-year low of 15.1%, driven by quarterly net sales of $15.1 billion. This is not a blip — between September 2023 and June 2026, FPIs recorded the sharpest decline in free-float ownership among all key non-promoter stakeholders in the Nifty 50, dropping 7.8 percentage points.
The West Asia conflict has compounded the pain. Rising energy prices heightened concerns about India's growth prospects following the US-Iran war, which triggered a surge in global crude oil prices — and those concerns are returning as energy prices rise again, with no clear resolution to the conflict. For a large oil importer like India, that translates directly into a weaker rupee, higher import bills, and compressed corporate margins.
Why Indians Are Buying Anyway
Equity mutual funds recorded a net inflow of ₹29,328.62 crore in August, an increase of about 19% from the previous month, according to AMFI. SIP contributions touched a record ₹32,297 crore in August, compared with ₹31,961 crore in July and ₹28,265 crore in August 2025.
This isn't irrational exuberance — it's a structural shift. Domestic mutual funds expanded their stake for the 12th consecutive quarter, as systematic retail participation offset sustained FPI selling. A decade of financial inclusion — Jan Dhan, UPI, the growth of low-cost broking — has created a new class of investor whose default response to a falling market is to add more SIPs, not cancel them.
Total DII share rose to 19.5%, maintaining its lead over FPI ownership for the seventh consecutive quarter, with the widest spread recorded since 2001.
The Risk Neither Side Is Pricing In
The divergence is not costless. Foreign outflows weaken the rupee, which raises the cost of crude imports, which feeds inflation, which erodes the real returns that retail investors are counting on. The irony: the more confidently Indian retail buys, the more it cushions the market against FPI selling — but it doesn't fix the macro.
Indian equities still command a 77% valuation premium to MSCI's emerging-market benchmark, prompting foreign funds to pull about net $25 billion this year and deploy it elsewhere. Until that valuation gap narrows — or India develops a credible AI-era corporate story — the two-way traffic is unlikely to resolve.
For now, the market has two very different owners with two very different time horizons. The question is which one blinks first.
Sources
- India Replaces Indonesia as Asia’s Least-Favored Stock Market in BofA Survey - Bloomberg
- FII ownership falls to 17-year low as domestic investors strengthen grip | Markets News - Business Standard
- India becomes the least-favoured stock market in Asia. What has investors worried?
- Equity mutual fund inflows jump 19 pc to Rs 29,328.62 crore in August: AMFI data
- Equity MF inflows jump 19% to Rs 29,329 crore
- Global funds turn wary of Indian stocks as AI boom draws money elsewhere | Markets News - Business Standard